Retirement Corpus Calculator With Inflation and SIP
This retirement corpus calculator with inflation shows the corpus your future income may need, the gap that remains, and the monthly SIP that could help close it.
Retirement isn’t simply the day work ends. It’s the start of a phase where what you’ve built has to support the life you want to live. Expenses change, inflation doesn’t stop, and the years ahead may be longer than you expect. The question isn’t only “How much should I have?” but “Will what I’ve built support the life ahead?”
Enter your numbers below to find out.
Your InvesTales Retirement Blueprint
An illustrative data engine from InvesTales. Adjust the sliders and see your Blueprint update live.
Kurma Phase: Tactical Enhancements
Mutual Fund Distributor: Arvind Arora | AMFI Registration Number: ARN-56507. Mutual fund investments are subject to market risks, read all scheme related documents carefully. This tool is illustrative only and does not guarantee returns.
Get your Blueprint Report
Share your details and we will open the printable report.
The Number Is a Starting Point
A calculator can show you a number. It cannot tell you what the number is for. Retirement is about more than building a corpus. It is about income, flexibility and security for the years ahead.
Build for tomorrow. Live from what you've built.
What Your Blueprint Shows
- The Retirement Gap: the corpus you may need at retirement, less what your existing portfolio may grow to.
- Monthly Taru SIP: an illustrative monthly amount, with an optional yearly step-up, that could help build that gap.
- Cost of Delay: how much more you would need to invest every month if you start 12 months later.
- Compare retirement ages: two retirement ages side by side.
- Narrative Story and Blueprint Report: your numbers in words, and a report you can save or print.
How Inflation Changes Your Retirement Corpus
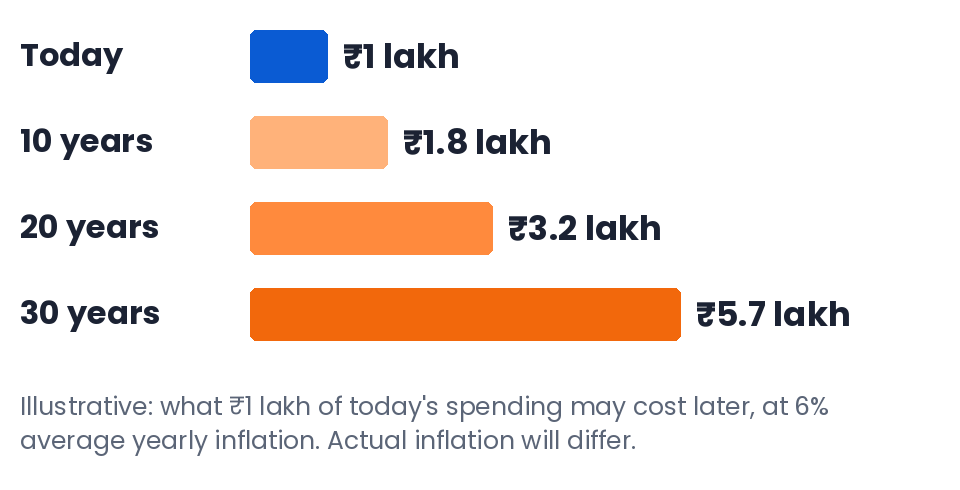
Most people think about retirement in today’s money. A retirement corpus calculator with inflation does the opposite. It carries your expenses forward to the year you retire, and keeps raising them through retirement. For example, ₹75,000 a month today could need about ₹3.2 lakh a month at age 60 if inflation averages 6% and you are 35 now. That is why a corpus that looks comfortable today can fall short later. Try your own numbers above, then move the inflation slider to see how sensitive the result is.
How This Retirement Corpus Calculator Works
Your Blueprint follows Taru and Kurma. The Taru Phase covers your earning years, when you build. The Kurma Phase covers retirement, when what you've built is used.
It starts from your monthly spending today, carries it forward at the inflation rate you choose, and estimates the corpus those years may need.
You may add other income, travel, medical costs and a 12.5% long-term capital gains (LTCG) tax allowance. The default assumptions are 12% a year before retirement, 8% after, and life expectancy of 85. You can change all three.
Questions People Ask
How much retirement corpus do I need?
How much retirement corpus do I need?
It depends on what you spend, how long retirement may last, inflation and the returns you assume. The calculator works it out from your own numbers, so your answer will differ from anyone else’s.
Does this retirement corpus calculator include inflation and tax?
Does this retirement corpus calculator include inflation and tax?
Yes. You choose the inflation rate, and you can switch on an allowance for 12.5% long-term capital gains tax, a travel fund and medical costs. All of them are assumptions you control.
Why 12% before retirement and 8% after?
Why 12% before retirement and 8% after?
They are assumptions, not promises. Returns vary, and some years are negative. You can change both to see a range of outcomes.
Why does inflation matter so much?
Why does inflation matter so much?
At 6% inflation, today’s costs more than quadruple in 25 years. A monthly expense that feels comfortable now can look very different at retirement.
Is this calculator free to use?
Is this calculator free to use?
Yes. Use it as often as you like. Your name and mobile number are asked only if you choose to download the Blueprint Report.
Is my information stored?
Is my information stored?
The calculations run in your browser. Your details are saved only if you download the report and tick the consent box, as explained in our Privacy Policy.
- Mutual Funds Sahi Hai: AMFI’s investor education site
- SEBI Investor website
Continue Your Journey
Protect your health and income before they disrupt the Blueprint: Protect.
Before you invest, understand your purpose and risk: Invest.
Read the full story: Retirement.
Not sure where to start? Talk it through on WhatsApp.
Disclosure
Mutual fund distribution is provided by Arvind Arora (AMFI Registered Mutual Fund Distributor), ARN-56507, valid 02 April 2025 to 01 April 2028. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This calculator is illustrative. Its results depend on assumptions, are not guaranteed, and are not a recommendation to buy, sell or hold any financial product. Privacy Policy